What Credit Score Do I Need to Buy a Home in Vancouver, WA in 2026?
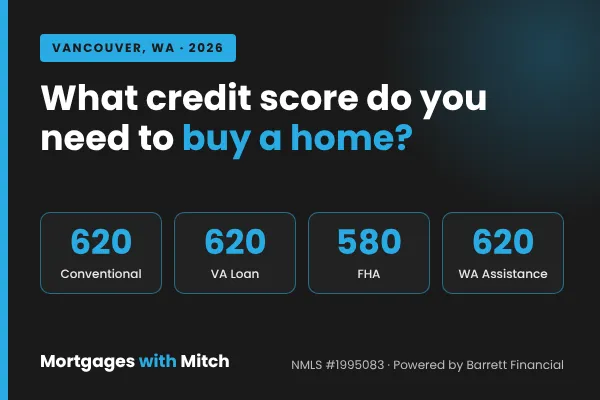
Quick answer: In Vancouver, WA in 2026, most buyers need about a 620 credit score to get a conventional or VA loan, as low as 580 for FHA, and 620 to use Washington's Home Advantage down payment assistance, even though Fannie Mae no longer sets a hard minimum for conventional loans.
Written by Mitch Tugaw, Mortgage Loan Officer, NMLS #1995083, Mortgages With Mitch, Powered By Barrett Financial LLC, serving the Portland, OR / Vancouver, WA metro since 2020
This is the question I get more than any other from first-time buyers in Clark County. The answer depends on the loan, so here's how it really breaks down right now.
Credit score by loan type (2026)
- Conventional: about 620. Fannie Mae dropped its official 620 minimum for automated approvals in November 2025. In practice, most lenders still want 620, and below 740 you'll pay more in rate and mortgage insurance.
- VA: about 620. The VA itself doesn't set a minimum. The lender does, and 620 is where most of them land.
- FHA: 580 with 3.5% down. HUD allows 500 to 579 with 10% down, but very few lenders will go that low.
- Washington Home Advantage down payment help: 620. This is the Washington State Housing Finance Commission (WSHFC) program most Clark County first-time buyers use.
What most articles get wrong
You'll probably read online that "conventional loans don't have a minimum credit score anymore." On paper, that's true. Fannie Mae removed the 620 cutoff from its underwriting system for loans started on or after November 16, 2025.
Here's what those articles leave out: the lenders who actually fund the loan still set their own floors. From what I'm seeing in Vancouver and Portland, 620 is still the realistic floor for a conventional loan. A file at 600 might get through the automated system and still be turned down by the lender.
Washington adds one more wrinkle. Even if a lender takes a score under 620, WSHFC down payment assistance still requires 620 in most cases. So a buyer at 610 could qualify for the loan and still miss out on the help that was supposed to cover their down payment.
Also, if you're comparing both sides of the river, Oregon's assistance programs don't work in Vancouver, and Washington's don't work in Portland. It's a common mix-up.
Which score do lenders actually use?
- Lenders pull all three bureaus and use your middle score, not the highest one.
- With two borrowers, the lower middle score usually decides the pricing.
- The score on your credit card app or Credit Karma is usually a different model, so expect your mortgage score to land somewhere else. It might even be a little lower.
Three myths I hear every week
- "I need 740 or higher to buy." You don't. A score of 740+ gets you the best pricing, but plenty of buyers close in the 620 to 700 range.
- "Getting pre-approved will wreck my score." Mortgage credit checks within a short window count as one inquiry. A pre-approval usually costs a few points, not 50.
- "VA loans need 640." That's just one lender's rule. Different lenders have different floors, so being told no once doesn't settle it.
If you're under 620 right now
Don't apply blind. Bringing your credit card balances under 30% of the limit (under 10% is better) and fixing errors on your report can move a score 20 to 40 points within a couple of billing cycles. A loan officer can run "what if" scenarios that show which payoff gets you the most points per dollar.
Let's look at your actual numbers
I'm a mortgage broker serving Clark County, Multnomah County, and the surrounding metro, and I work with conventional, VA, FHA, and Washington's WSHFC down payment programs. Lenders set different credit floors, so working with a broker who has access to sharp pricing means you're not stuck with one bank's answer. If you're at 600 and wondering whether you're close, email me at [email protected] and I'll tell you where you stand and what it'll take.
This article reflects information as of October 2026. Terms and eligibility change. Confirm current details with a licensed loan officer before making financial decisions.
Mitch Tugaw is a mortgage broker (NMLS #1995083) with Mortgages With Mitch, powered by Barrett Financial LLC, an Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and program availability.


